
Approved roofing work may qualify
Florida PACE can include eligible roof repair, replacement, deck-attachment, secondary-water-barrier and related permanent improvements.
Planning a roof replacement or repair? Start with a free M&M Roofing estimate and information about Home Run PACE financing. Eligible projects in participating Palm Beach County communities may qualify, subject to property and owner approval. PACE is repaid through the property-tax bill and creates a lien on the home.
M&M Roofing license CCC1332459
Home Run handles the application, terms and approval directly
Tell us the property ZIP code and roofing need. We will follow up to discuss the roof and check the jurisdiction.
This sends an information request to M&M Roofing. It is not a financing application or approval. Home Run sends its secure application directly to the property owner.
Home Run's Florida PACE program is property-assessed financing. It is different from a traditional personal loan and carries obligations that should be compared carefully.
Florida PACE can include eligible roof repair, replacement, deck-attachment, secondary-water-barrier and related permanent improvements.
The financed amount, interest and fees are repaid as an annual non-ad valorem assessment that creates a recorded lien on the property.
Home Run—not M&M Roofing—sets the rate, APR, fees, annual assessment, term and approval decision in the official financing documents.
Home Run says it does not use the applicant's score to determine eligibility, but it still reviews credit information and verifies ability to repay.
Home Run does not currently list every Palm Beach County municipality. Its public Florida communities page lists the seven places shown here, so an address in another city should not be treated as eligible without updated provider confirmation.
Roofing-service coverage does not guarantee PACE availability. The exact property address must be checked.
View Home Run's current Florida listChecked against Home Run's public Florida communities page on September 29, 2026. Participation and program terms can change.
Start with the roof
A useful financing conversation starts with a clear roofing scope. The condition of the deck, the roof system and the work needed at edges and valleys all help shape that estimate.
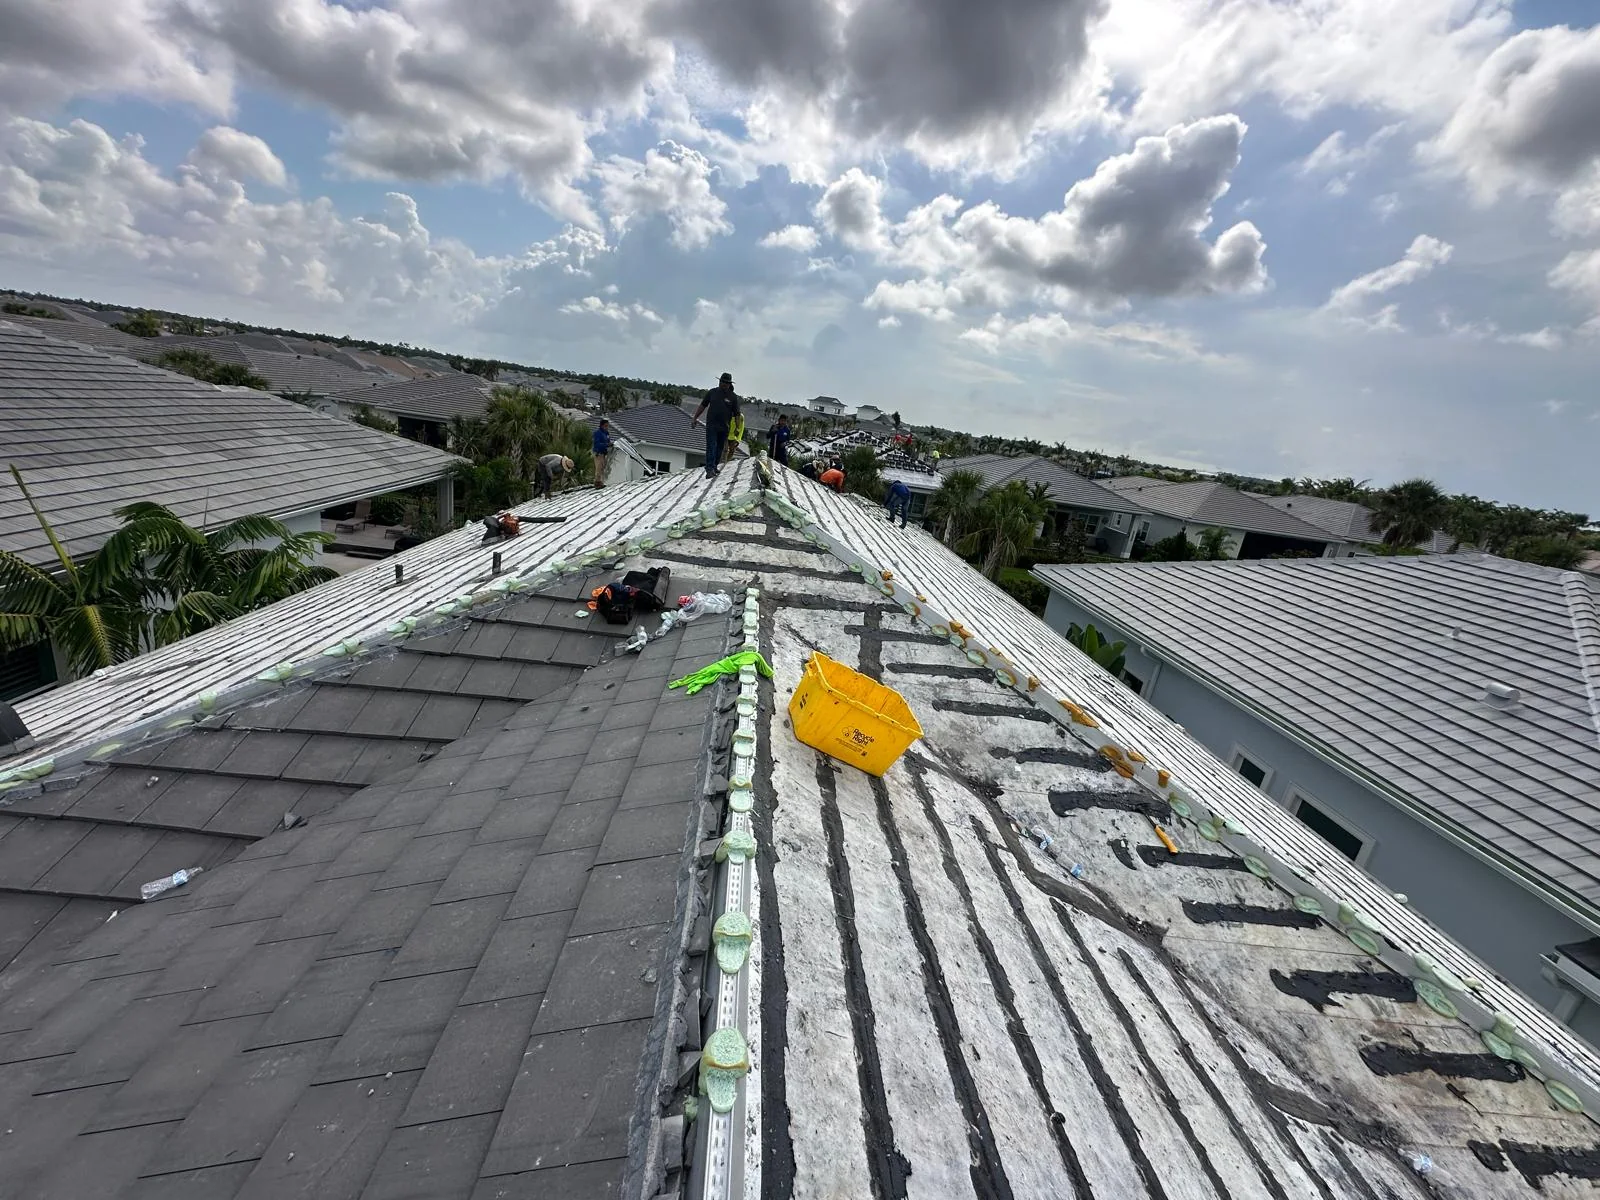
Our project photos follow the work from property protection and tile removal to the exposed wood deck and Polystick TU MAX underlayment installation. These stages show why a roof proposal needs to describe more than the visible roof covering.
For your own project, ask how tear-off, deck preparation, any needed wood repairs and the dry-in system will be handled. M&M can assess your roof and prepare a written estimate before you review financing terms with the provider.
Explore the roofing work first, then use your estimate to discuss the financing amount. Calculator figures are planning estimates, not a roofing quote or financing offer.
Understand the scope, materials and steps in a replacement.
Explore repairs when the roof condition supports them.
Look beyond the tile to the roof system underneath.
Start a planning budget, then request a property-specific quote.
Keep the written roofing estimate beside the provider’s disclosures. Before signing, review these details together:
M&M Roofing evaluates the roof and prepares the project scope and estimate.
We confirm that Home Run lists the property's jurisdiction and that the proposed roof work can be submitted for program review.
M&M initiates the request when appropriate. Home Run sends the owner its secure application and collects qualification information directly.
Home Run reviews the property and ability to repay and provides the financing disclosures. At least five business days before the agreement, it gives the mortgage holder or servicer written notice of the intent, maximum financed amount and maximum annual assessment.
PACE-financed work begins only after approval, notice to proceed and required waiting and cancellation periods.
The project and required permit closeout are verified before final funding. The assessment then appears on the property-tax bill.
Read the official Home Run documents and compare the total cost with other ways to pay before signing.
M&M Roofing is not a lender and does not provide legal, tax or financial advice. Home Run Financing determines eligibility, approval, rate, APR, fees, annual assessment and term.
Contractor registration or project approval does not mean Home Run Financing or the Florida PACE Funding Agency endorses, warrants or guarantees M&M Roofing or its work.
M&M helps homeowners explore Home Run's PACE option for eligible roofing work. This is property-assessed financing, not a monthly installment plan paid to M&M. Repayment is collected on the property-tax bill; a mortgage servicer may adjust monthly escrow payments. Home Run determines eligibility and provides the actual terms.
No. Palm Beach County includes separate municipalities. West Palm Beach is on Home Run's list checked September 29, 2026; the Town of Palm Beach is not on that list. A county name or mailing address alone does not establish eligibility. Confirm the exact property with Home Run before applying.
Yes. Request a free M&M Roofing estimate first so you can review the proposed repairs or replacement and the project price. Sending this site's form is an information request, not a financing application or a commitment to use PACE.
Have the property address, roof type, a description of any leaks or damage and your preferred timing ready. We use the roof assessment to prepare a written scope. If you decide to apply, Home Run collects the financial qualification information through its secure application.
No. PACE authorization is jurisdiction-specific. A roofing company may serve a property even when the financing program is not available there. The exact address must be checked against Home Run's current community list.
Do not treat PACE as no-credit-check financing. Home Run says the credit score is not used to determine eligibility, but it may obtain credit information and must verify income, debts, mortgage obligations, taxes, insurance and ability to repay.
The approved amount depends on the eligible project, property value, local limits and underwriting. Home Run provides the actual fixed rate, APR, fees, annual assessment and total cost. M&M Roofing does not quote financing payments or promise approval.
Home Run permits an assessment to remain with the property, but a buyer or either party's mortgage lender may require full payoff during a sale or refinance. The seller must also provide the required property disclosure.
Home Run advertises up to 100% financing for eligible project costs, subject to approval. Florida generally limits total PACE assessments to 20% of the county property appraiser's just value; local rules, underwriting or ineligible work may lower the approved amount.
The main financing guide explains eligibility, the tax assessment, lien, sale and refinance considerations, cancellation and the Home Run process in more detail.
We can review the roofing need and check whether the current Home Run community list includes the property's jurisdiction.